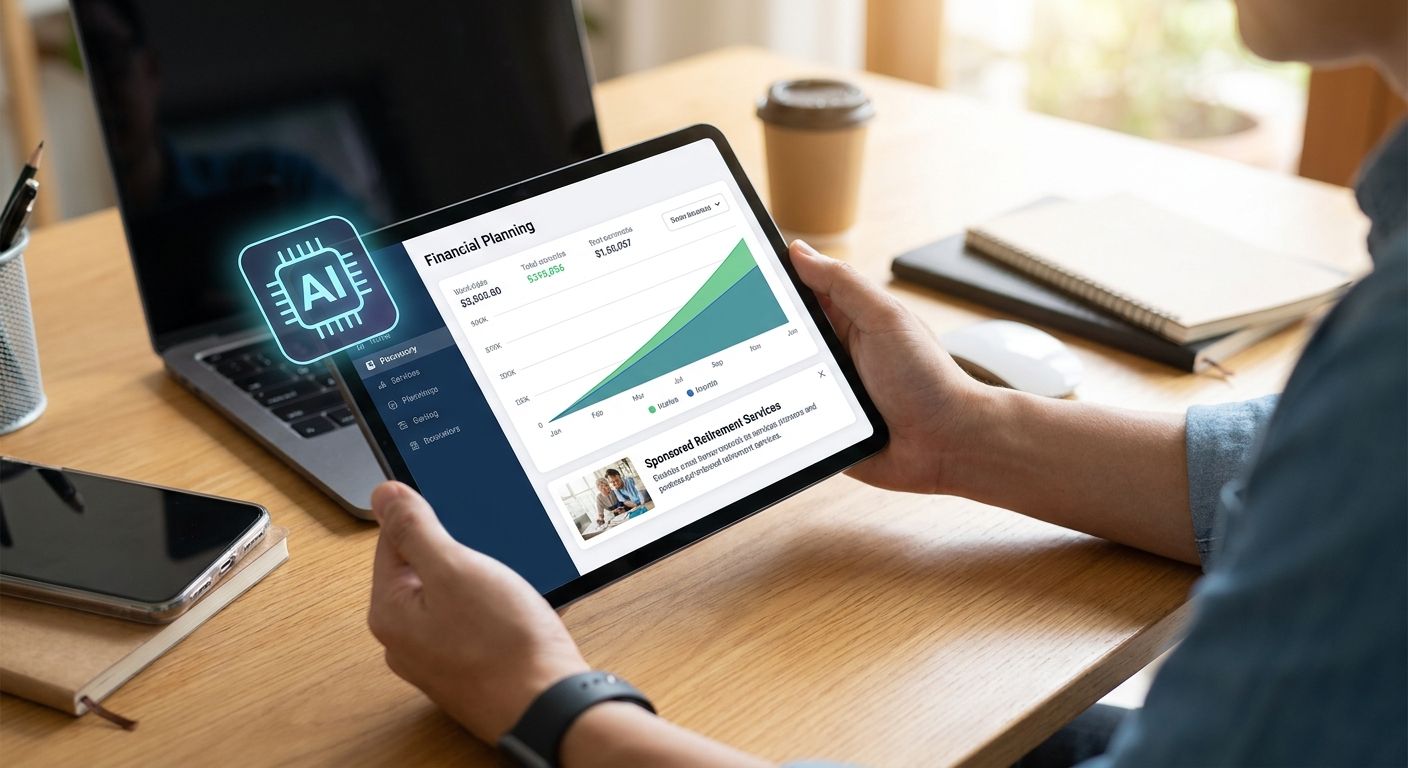
Ad monetization for AI retirement planning apps is the practice of embedding contextual, in-chat ads inside retirement-planning conversations so every session earns revenue, not just the ones that convert to a paid tier. A user asking about 401(k) rollovers, IRA contribution limits, or Social Security claiming age is closer to a purchase decision than someone chatting with a general-purpose assistant, and that intent is worth more to an advertiser than a passing question about the weather.
- Ad monetization for AI retirement planning apps works best with native in-chat cards, not banners.
- Free-tier users asking about annuities or 401(k) rollovers are high-intent — monetize them instead of gating everything behind a paywall.
- Financial-vertical chat ads need brand-safety and disclosure rules that generic ad networks don't enforce by default.
- Elo's SDK ships in twelve lines of code, which matters when you're not staffing an ad-ops team.
Why ad monetization matters for AI retirement planning apps
Retirement planning conversations are long. Users move from 401(k) rollover math to Social Security claiming age to Medicare enrollment windows inside the same thread, often across 20 or more messages. Each of those topics maps to an advertiser category that already buys media elsewhere — annuities, robo-advisors, insurance carriers, tax-prep services.
That's different from a generic productivity bot, where most turns don't map to a purchasable product at all. A retirement planning assistant has a built-in monetization surface most chat apps have to manufacture. Elo's SDK is built to serve a native ad card inside that surface without breaking the multi-turn flow the conversation depends on.
The segment also carries more scrutiny than a recipe bot or a trivia app. Money advice attracts regulators, and a sponsored card that reads like unbiased guidance is a fast way to lose user trust. Monetization here has to work around that constraint, not against it.
Map where retirement conversations create ad opportunities
Start by logging where your own conversations already cluster before you build anything. The manual version of this is just conversation review; the automated version comes later.
- Tag turns that mention 401(k) rollovers, IRA transfers, or annuity comparisons
- Flag Social Security claiming-age questions — high commercial intent, recurring across sessions
- Track Medicare enrollment window questions as a seasonal spike, not a steady baseline
- Separate calculator or tool usage from open-ended advice questions
- Note which turns end a session versus which continue into deeper planning
Decide which users see ads and which don't
Not every user in a retirement planning app should see a sponsored card. Get this segmentation right before you touch ad formats.
- Serve ads to free-tier and anonymous users only if a paid tier exists to protect
- Keep paying subscribers ad-free — ads next to a paid plan undercut the upgrade case
- Cap ad frequency per session before rolling out to all free traffic
- Exclude sessions where a user discloses a health crisis or major life event affecting their retirement timeline
Pick ad formats that fit a financial conversation
A banner bolted onto a chat sidebar reads as spam next to a retirement calculation. The format has to sit inside the conversation, not next to it.
- Use native cards that render inline with the assistant's response, not display banners
- Reserve one ad slot per session milestone — after a rollover comparison, for example — rather than one per message
- Test text-only sponsored suggestions for slower connections before adding rich media
- Skip interstitials that block the next input; retirement math spans multiple turns
- Let an SDK handle card rendering and format fallback instead of building a rendering pipeline from scratch — monetizing an AI chatbot with conversational ads covers the mechanics if you haven't shipped one before
Match ads to context instead of guessing
Generic finance keyword matching misses the point. Retirement conversations need retirement-specific categories.
- Build clusters around 401(k), IRA, annuity, Medicare, and Social Security terms instead of broad "finance" tags
- Match at the turn level, not the session level — a user who moved from annuities to estate planning needs a different match
- Downweight sponsored slots mid-calculation so a card doesn't interrupt a multi-step answer
- Rotate matched categories across a long session so the same annuity ad doesn't repeat five times in one thread
Build compliance and brand safety before launch
This is the step most chat apps skip and the one that gets a retirement planning app flagged.
- Add a disclosure line to sponsored cards so users know it's an ad, not assistant-generated advice
- Exclude conversations with distress signals or elder-financial-abuse red flags from ad delivery entirely
- Block advertiser categories that make explicit return guarantees next to your own retirement projections
- Keep a log of what ad ran against what conversation turn in case a partner or regulator asks
- Review keeping conversational ads brand safe before the first advertiser goes live, not after
Test the integration before you ship it
A broken ad card in the middle of a rollover comparison is worse than no ad at all.
- Run the integration in staging against real sample retirement conversations first
- Check ad card render time against your existing response latency budget
- Confirm ad card taps don't break the chat thread on mobile
- Verify frequency caps hold across a 30-plus message session, common for multi-step retirement planning
Measure revenue per session and iterate
Once ads are live, the work shifts from setup to tuning.
- Track revenue per thousand sessions split by free versus anonymous traffic
- Compare fill rate on financial-category ads against your overall matcher fill rate
- Watch for declining tap-through after the third card in a single session — an ad fatigue signal
- Re-tune the matcher each quarter as advertiser demand shifts around open enrollment season
“A retirement planning bot that only monetizes conversions is leaving every free-tier conversation on the table.”
Add ads to your retirement planning assistant
Native in-chat cards, matched to conversation context, not banners.
Comparison: monetization options for AI retirement planning apps
| Option | Best for | Monetization model | Key limitation |
|---|---|---|---|
| SDK-based contextual ads (Elo) | Apps with an active chat surface and free-tier traffic | Advertiser spend via native in-chat cards | Needs a conversational surface to render into |
| Traditional display/banner networks | Web wrappers with sidebar or footer space | CPM-based display inventory | Breaks conversational UX, feels bolted-on next to chat |
| Direct affiliate deals with advisors or robo-advisors | Low-volume apps with high-intent, qualified users | Referral commission | Manual deal-making, slow to scale past a handful of partners |
| Subscription/freemium paywall only | Apps with a clear premium calculation or planning feature | Recurring subscription revenue | Zero revenue from the free-tier chat volume that never upgrades |
Verdict: for a retirement planning assistant with meaningful free-tier chat volume, native in-chat ad monetization wins over banner networks and beats leaving free users unmonetized — direct affiliate deals stay a good complement at low volume, not a replacement.
Common mistakes retirement planning apps make
- Running generic ads instead of finance-matched ones. An entertainment ad card next to a Social Security claiming-age question looks careless and gets ignored.
- Skipping disclosure language. A sponsored card that reads like assistant advice erodes trust fast in a category built on trust.
- Interrupting mid-calculation. Dropping an ad card in the middle of a rollover comparison breaks the flow the user came for.
- Monetizing paying subscribers. Ads next to a paid plan undercut the reason someone upgraded in the first place.
- Treating ad tuning as one-and-done. Advertiser demand in the retirement category shifts around open enrollment and tax season; a matcher tuned once in January is stale by fall.
FAQ
What's the best way to monetize an AI retirement planning app in 2026?
Native in-chat ad cards matched to conversation context work best for retirement planning apps in 2026 because the conversations already map to advertiser categories like annuities, IRAs, and Medicare. Banner networks and paywall-only models leave free-tier session volume unmonetized.
Is ad monetization better than a subscription-only model for retirement planning assistants?
Ad monetization and subscriptions solve different problems — ads monetize the free-tier and anonymous traffic a subscription model ignores entirely. Most retirement planning apps run both: subscriptions for premium calculators, ads for everyone else.
How long does it take to integrate an ad SDK into a retirement planning chatbot?
Elo's SDK integrates in twelve lines of code, which is closer to a config change than a build project. Testing against real retirement conversation flows still takes longer than the integration itself.
Do ads inside a retirement planning chatbot need financial disclosures?
Yes — a sponsored card that isn't labeled as an ad reads as assistant-generated advice, which is a trust problem in a financial-adjacent category. Add a disclosure line to every sponsored card before launch.
Should paying subscribers see ads in a retirement planning app?
No. Serving ads to paying subscribers undercuts the reason they upgraded and creates a worse experience for your highest-value users. Reserve ad delivery for free-tier and anonymous traffic.
What ad format works best inside a financial chat conversation?
Native cards that render inline with the assistant's response outperform banners and interstitials because they don't break the multi-turn flow retirement math requires. Text-only sponsored suggestions work as a fallback on slower connections.
How do I avoid ad fatigue in a multi-turn retirement planning conversation?
Cap ad frequency per session and rotate matched categories so the same annuity or IRA ad doesn't repeat across a 20-plus message thread. Declining tap-through after the third card in one session is the signal to pull back.
Can a retirement planning chatbot run ads and still give unbiased advice?
Yes, as long as sponsored cards are clearly disclosed and separated from the assistant's own calculations and recommendations. The moment a sponsored card looks like assistant-generated advice, the perceived bias problem starts.
One last thing
Medicare's Annual Enrollment Period runs October 15 through December 7 every year — a retirement planning app that doesn't retune its ad matcher ahead of that window is missing the single biggest seasonal demand spike in the category, then wondering in January why fill rates dropped.